The ECO and the Future of West African Integration
The leaders of the Economic Community of West African States reaffirmed the priority of advancing the ECO currency project. ECOWAS has retained 2027 as the target contained in its existing roadmap, although the eventual launch is expected to depend on countries meeting the required conditions.
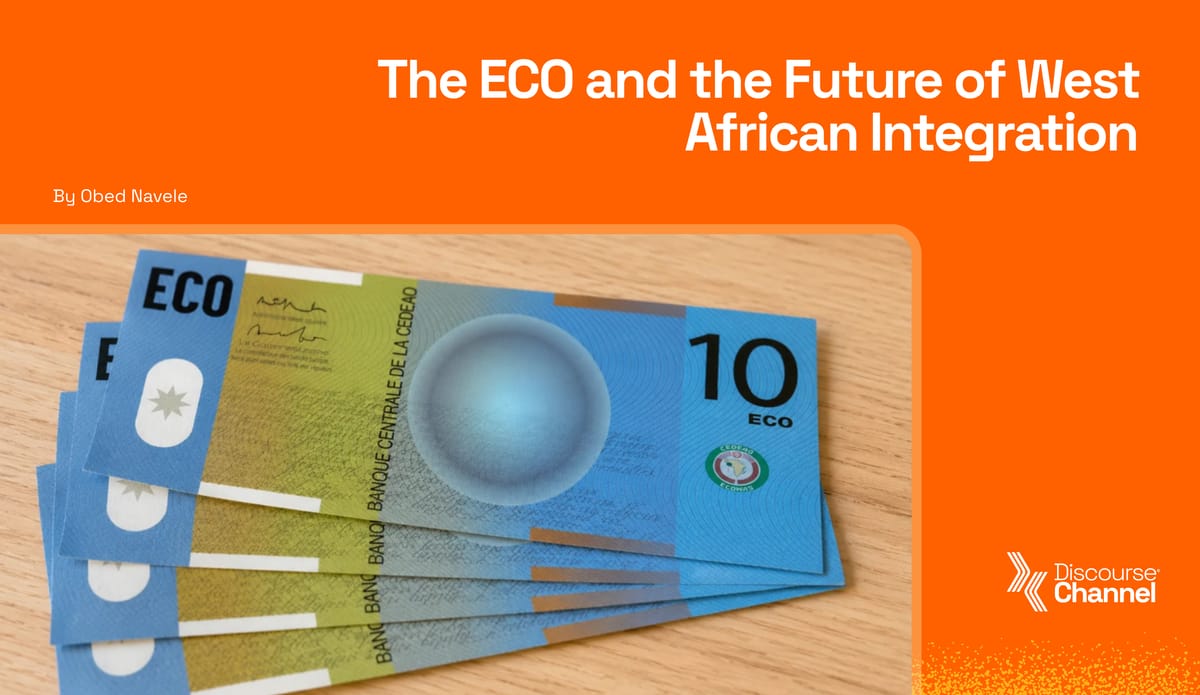
For generations, African integration has been spoken about as an aspiration. The continent has established regional organisations, negotiated free-trade agreements, negotiated border restrictions, and repeatedly affirmed its commitment to political and economic unity. Yet for millions of African businesses and citizens, the practical experience of the continent remains one of fragmentation. Goods cross borders slowly. Payments frequently pass through foreign financial centres. Traders operating between neighbouring African countries must often acquire dollars or euros before completing transactions with one another. Currency fluctuations can erase already narrow margins, while conversion fees make regional commerce more expensive than it needs to be.
The proposed ECO could begin to change that. At their summit in Freetown, Sierra Leone, on July 19, 2026, the leaders of the Economic Community of West African States reaffirmed the regional priority of advancing the ECO single-currency project. ECOWAS has retained 2027 as the target contained in its existing roadmap, although the eventual launch is expected to depend on participating countries meeting the required economic and institutional conditions. The regional body continues to describe economic integration and interconnectivity as one of its central strategic priorities. The decision matters not only for West Africa. It could represent the beginning of a larger transformation in how Africa trades, finances its development and understands its collective economic power. The ECO will not, by itself, create African unity. But a credible, independently governed and properly constructed common currency could become one of its most tangible expressions.
More Than a Change of Banknotes
A shared currency is sometimes presented as a largely technical undertaking involving central banks, inflation targets and foreign-exchange reserves. In reality, it is a profoundly political project. A currency determines how value is measured, how commerce is conducted and who ultimately controls monetary policy. It affects the price of food, the availability of credit, the cost of imports, the competitiveness of exports and the ability of governments to respond to economic crises. For West Africa, the ECO therefore raises a defining question: can countries with different economic structures pool part of their national monetary authority in exchange for greater regional power?
The potential rewards are considerable. A common currency could reduce the costs and uncertainties that come with converting between the naira, cedi, leone, dalasi, Liberian dollar, Guinean franc, escudo or CFA franc. It could make prices more transparent across borders, improve the predictability of regional contracts and help small and medium-sized businesses enter markets that currently appear administratively or financially inaccessible. It could also make West Africa more legible to investors. Rather than approaching a collection of fragmented monetary jurisdictions, businesses could increasingly view the region as an interconnected commercial area governed by common rules and supported by an integrated financial system. The greatest benefit, however, would be psychological as much as financial. A common currency would tell West Africans that regional integration is not simply something discussed at summits. It is something they can hold, earn, save and use.
The Sahel and a Changing West African Monetary Map
The emergence of the Alliance of Sahel States adds another layer of complexity. Mali, Burkina Faso and Niger have withdrawn from ECOWAS and established a confederation intended to deepen their political, security and economic cooperation. The three governments have spoken forcefully about sovereignty, self-reliance and reducing their dependence on external powers. They have also announced plans for closer cooperation in areas including infrastructure, investment and regional development.
This has naturally generated speculation that the three countries could eventually establish their own central bank and currency. That possibility should not be dismissed over the longer term. A shared Sahelian currency could conceivably become part of the alliance’s pursuit of greater institutional autonomy. It would also represent a direct challenge to the continued use of the CFA franc.
But it is important not to present speculation as fact. Mali has rejected reports that an imminent three-state Sahel currency is being prepared, describing those claims as false. Mali, Burkina Faso and Niger also remain members of the West African Economic and Monetary Union and continue to use the CFA franc. Leaving ECOWAS did not automatically remove them from the separate monetary union. The Sahel states therefore occupy an unusual position. Politically, they are constructing a new regional bloc outside ECOWAS. Monetarily, they remain within a CFA-franc system shared with several ECOWAS countries. Over time, they may face a choice between remaining within the existing West African monetary union, establishing a separate Sahelian currency, or negotiating some form of participation in a future ECO.
The most constructive outcome would prevent political disagreement from producing permanent economic fragmentation. West Africa’s long-term interests are not served by creating multiple incompatible monetary spaces that make regional trade more difficult. A future ECO should therefore retain an open architecture. Even if Mali, Burkina Faso and Niger do not participate at the beginning, there should be a credible path through which the Sahel states could eventually align with or join a wider West African monetary area. Regional sovereignty should not require regional separation.
The Challenge of Building One Monetary Policy
The case for the ECO is powerful, but optimism should not require pretending that monetary union is easy. West African economies do not move in perfect alignment. Nigeria is a major oil producer, while many neighbouring countries are oil importers. A rise in energy prices can benefit one economy while damaging another. Agricultural cycles, government debt, inflation, foreign-exchange reserves and levels of industrial development also vary considerably across the region. A common central bank would have to establish one monetary policy for countries experiencing potentially different economic conditions. The interest rate required to contain inflation in one member state may be inappropriate for another confronting unemployment or weak economic growth.
That is why convergence criteria matter. Countries entering a monetary union must demonstrate sustained discipline in areas such as inflation, public debt, fiscal deficits and central-bank financing of government expenditure. They must also improve the quality and comparability of their economic statistics. Without this preparation, financially stronger members could be required to absorb the consequences of weaker fiscal management elsewhere. Individual governments would also lose some of the tools they currently use during crises, including unilateral currency devaluation and the independent adjustment of interest rates. The ECO has missed previous target dates because the necessary convergence has proven difficult to achieve consistently. That history should encourage preparation, but it should not become an argument for permanent postponement. The phased approach may therefore be the most realistic path forward. Rather than waiting indefinitely for every country to meet every requirement at precisely the same time, a smaller group of prepared states could establish the first ECO area. Other countries could enter once they achieve the required economic and institutional standards. That model would allow momentum without abandoning discipline. But the entry rules must remain transparent and credible. Political considerations cannot override economic readiness, and participation cannot become a symbolic prize distributed by heads of state. A common currency requires a common standard.
A real economy must accompany a currency
The ECO cannot become a substitute for industrial policy. A region does not become economically integrated simply because its countries use the same money. Roads must connect production centres to markets. Customs systems must communicate with one another. Electricity must be reliable. Capital must reach businesses. Agricultural and industrial standards must be harmonised, and restrictions that continue to impede the movement of goods must be removed.
Otherwise, West Africa risks creating a common currency without creating a sufficiently integrated productive economy beneath it. The ECO should therefore be understood as one component of a larger regional project. It must operate alongside the ECOWAS Trade Liberalisation Scheme, regional infrastructure investment, integrated energy markets, freedom of movement and the African Continental Free Trade Area.
The objective is not merely to make it easier to purchase imported products in a shared currency. It is to make it easier for cocoa processed in Ghana to be sold in Senegal, for Nigerian manufacturing inputs to reach factories in Côte d’Ivoire, for Senegalese financial services to enter Sierra Leone and for regional capital to finance regional industry. It should make it easier for West African minerals to be processed within West Africa, for agricultural commodities to be transformed into finished products and for the value created by regional resources to remain within regional economies. The real measure of the ECO will be whether it increases the amount that West Africans produce for, purchase from, and invest in each other.
Building the Financial Infrastructure of Integration
Africa does not need to wait for a single continental currency before reducing its reliance on dollars and euros in intra-African commerce. The Pan-African Payment and Settlement System already provides infrastructure through which cross-border payments can be initiated and received in African currencies. Instead of converting one African currency into a foreign currency before converting it again into another African currency, the system is designed to facilitate direct settlement across participating markets.
The ECO and continental payment infrastructure should not be viewed as competing ideas. A pan-African payment system can connect multiple currencies across the continent. The ECO can remove the requirement for currency conversion altogether within its participating West African area. Together, these instruments could create a layered African financial architecture in which regional currencies operate through a continental settlement network. That would help keep more African trade, liquidity, data and financial activity within African institutions.
East Africa Is Already Moving
West Africa is not alone in pursuing monetary union. The East African Community signed its Monetary Union Protocol in 2013 and is working towards establishing a single currency by 2031. The regional project includes plans for greater macroeconomic convergence, harmonised financial regulation, coordinated fiscal and monetary policy and the institutional foundations of an East African central bank. An East African currency could connect some of the continent’s most dynamic economies and trade corridors. Kenya’s financial and technological ecosystem, Tanzania’s scale and access to the Indian Ocean, Uganda’s agricultural and industrial potential, Rwanda’s services economy, the Democratic Republic of Congo’s mineral wealth, South Sudan’s energy resources, Burundi’s strategic location and Somalia’s commercial networks could form an increasingly powerful economic area. The benefits would extend beyond eliminating conversion costs.
A credible East African currency could deepen regional capital markets, allow companies to raise financing across a larger jurisdiction and strengthen the development of regional value chains. It could support trade from the ports of Mombasa and Dar es Salaam into the continent’s interior and create a larger monetary platform for infrastructure, energy and industrial investment. It could also strengthen East Africa’s position in global commerce. A currency representing a large, youthful and increasingly integrated market would possess greater negotiating and financial weight than the currencies of its individual members acting separately.
The region faces many of the same challenges as ECOWAS: uneven economic structures, debt vulnerabilities, differences in institutional capacity and concerns about the influence of the largest economies. But those challenges are not arguments against integration. They are arguments for building the institutions required to sustain it.
Regional Currencies as the Foundation of One African Currency
The emergence of strong regional currencies should not be understood as the alternative to a single African currency. It could be the pathway towards one. West Africa could build around the ECO. East Africa could complete its planned monetary union. Southern Africa could develop a common currency from the foundations already created by its existing trade, financial and monetary relationships. Central Africa could reform and Africanise its existing monetary structures, while North Africa could build deeper integration across its own economies and progressively connect with the monetary systems developing to the south.
These would not need to remain permanently separate blocs. Regional currencies could first be linked through compatible payment systems, coordinated financial regulation, common reserve arrangements and the architecture of the African Continental Free Trade Area. As regional trade, production, capital markets and fiscal coordination deepen, those monetary areas could move towards formal convergence. The long-term destination could be a single African currency supported by an African central bank and a genuinely continental financial system. Such a currency would represent a market of more than a billion people, immense natural resources, expanding cities, a young workforce and some of the fastest-growing consumer economies in the world.
It would not immediately displace the United States dollar, the euro or the Chinese yuan. Nor should its success be measured solely by whether it becomes a dominant global reserve currency overnight.
The ECO as a Statement of Intent
The ECO should not be judged solely by whether physical banknotes enter circulation in 2027. It should be judged by the quality of the institutions established around it, the independence of its central bank, the discipline of participating governments and the degree to which it expands productive trade between West African economies. A rushed launch without sufficient preparation could damage public confidence and set regional integration backwards. But perpetual delay carries its own cost. Every year in which neighbouring African countries must rely heavily on foreign currencies and external financial channels to trade with one another reinforces the fragmentation the continent has spent decades promising to overcome.
The answer is not to abandon ambition. It is to build the institutions capable of sustaining it. West Africa now has an opportunity to demonstrate that African integration can be practical, sovereign and economically consequential. If the ECO succeeds, it could encourage East Africa to accelerate its own monetary union, reopen a serious conversation about a shared currency in Southern Africa and provide a bridge through which the Sahel states can eventually participate in a wider West African financial system. From there, regional monetary areas could become the foundations of something even more consequential: a single African currency capable of representing the collective productive, commercial and demographic weight of the continent. The result would be greater than the creation of new banknotes. It would be the emergence of an African monetary system capable of negotiating, trading and investing at the scale the modern global economy demands.
Africa already possesses the population, natural resources, entrepreneurial capacity and expanding consumer markets required to become one of the defining economic forces of this century. What it has too often lacked is the infrastructure to combine that power. A common currency cannot create unity on its own. But it can make unity usable. The ECO may begin in West Africa. Its true significance, however, could be that it helps Africa finally build a currency, a market and an economic future equal to its continental scale.