AfCRA Launches to Contest Africa's Risk Premium. Delivery Is the Test.
Africa pays for how it is seen. A rating decides what a road, a clinic or a market stall costs to build. Mauritius has launched an agency to look closer. Will anyone in Africa's last mile feel the difference?
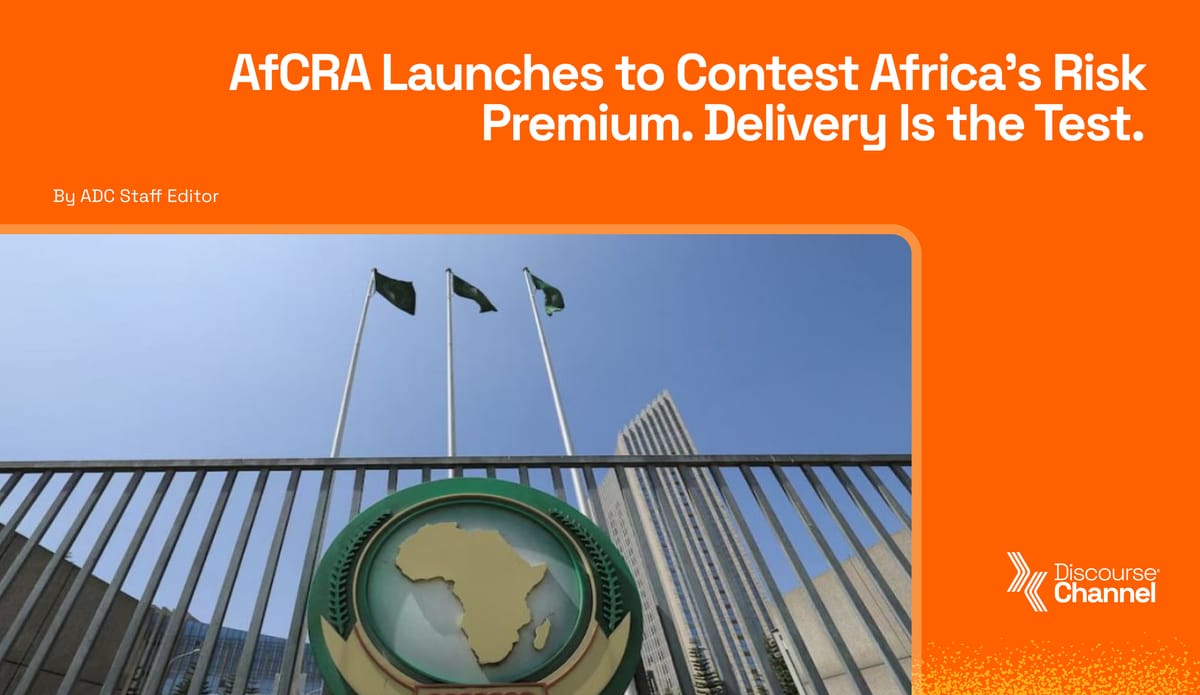
The African Union says African economies are rated B to B-minus on average, against BB for other emerging regions. It says that gap can limit some investors' participation and raise what Africa pays to borrow. On Wednesday, it launched an institution to contest it: the Africa Credit Rating Agency (AfCRA), based in Port Louis, Mauritius.
Facts
AfCRA will rate sovereigns, financial institutions and private companies. African leaders endorsed its creation in 2018, according to Reuters. The AU says it will operate independently, funded by shareholder capital and its own operations, though it has not said who the shareholders are. At the launch, Afreximbank's Denys Denya, whose institution is one of the backers, offered the case in one line: "When lenders don't see clearly, they charge for the fog."
The stakes are fiscal. The AU says Africa's external debt service rose to $163 billion in 2024 from $61 billion in 2010, and that in many countries interest payments have exceeded annual budgets for key social sectors such as health and education. Twenty-three African economies carry no rating from the three major agencies, the AU says.
ADC Analysis
Treat AfCRA as infrastructure, not as a rebuttal. A rating is a pricing layer beneath many large financing decisions. In many markets it influences the spread on a Eurobond and can determine whether an institutional investor's mandate permits a purchase. Depending on the jurisdiction, it can also shape how banks treat government paper for collateral and capital purposes. Where no rating exists, that machinery may not run. The 23 economies without a big-three rating are harder to price and, in many cases, likely to be less visible to institutional allocators. Some may be rated by other agencies.
Denya's framing matters because fog is an information problem, and information is built, not argued. An Africa-based rater is only as good as the data pipes feeding it: statistical offices, debt registries, central bank reporting and corporate disclosure. The AU's own readout points to this. The African Peer Review Mechanism (APRM) called on governments to supply accurate and timely information. The agency launched in Port Louis, but its quality will be decided in finance ministries and national statistics offices.
The last mile is where the argument gets tested. A higher sovereign spread tends to raise the benchmark for domestic bank lending. That benchmark can feed into the loan quote for a trader in Kumasi restocking before market day, a Nairobi logistics start-up financing a van, or a Lagos manufacturer importing inputs. These are illustrations, not reported cases. It can also mean a clinic waiting another budget cycle for equipment. The rating never appears on their invoices, yet it can sit inside the price.
If AfCRA's work narrows even part of the premium attached to information gaps, the effect could reach people furthest from Port Louis. That outcome is our analysis, not an AfCRA commitment. It depends on regulators and institutional investors writing AfCRA ratings into their eligibility rules. Without that step, a rating is an opinion nobody is required to read.
Room for Disagreement
The strongest objection is evidentiary. A 2024 Reuters investigation into Africa's debt crisis found no evidence of systemic bias in the sovereign ratings the three major agencies assign the region. The agencies reject the bias charge and say they apply the same methods everywhere. If bias is not the main driver, a new rater does not lower prices by itself. Fundamentals, debt structures and currency risk still do the pricing.
The second objection is credibility. Dennis Shen, a finance lecturer and former sovereign analyst at Scope Ratings, argues that a new agency starts with a promise while investors need a track record. He says the hardest test comes under market stress, when a rater's conclusions turn uncomfortable. Former Nigerian Vice President Yemi Osinbajo made the complementary point. AfCRA may provide a counterweight to the incumbents, he said, but it must meet global standards and cannot be a nationalistic agency.
The third objection is ownership. Capital structure is where independence is decided, and the shareholder list is not public. Reuters notes the AU gave no shareholder details, while Businessfront reports the AU saying governments cannot own shares. Afreximbank is a backer, and its shareholders include African sovereigns as well as private investors. That sits awkwardly beside a no-government-ownership rule, and the AU should clarify how the two fit.
There is also history. Afreximbank ended its rating relationship with Fitch on 23 January 2026, saying the agency's approach no longer reflected an understanding of the bank's mission and mandate. Fitch had downgraded it from BBB to BBB- in June 2025, citing its exposures to Ghana, South Sudan and Zambia, and the APRM publicly called that classification a misclassification. The APRM is the body tasked with establishing AfCRA. None of this shows AfCRA will be biased. But a backer and the institution that built the agency both took public positions against an incumbent rater, and a sceptical investor will bring that context. A lender with exposure to African borrowers supporting a rater of those borrowers is not disqualifying, but it is disclosure territory.
What Else Matters
The timing overlaps with wider plumbing work. Businessfront reports a recent AfCFTA digital trade corridor agreement involving Quest Ghana, pairing a commodities exchange with an interoperable payment system and aimed at expanding intra-African trade. If trade grows, it could create demand for credit assessments of firms that global agencies do not cover. That is our inference. It is where corporate and bank ratings, not just sovereign ones, could become commercially useful.
The AU Commission Chairperson said Mauritius was chosen for its established financial centre, regulatory framework and links to African and global markets, which gives AfCRA a credible home.
Solutions in Action
Four tests will show whether AfCRA works.
Methodology. Published criteria detailed enough that analysts can replicate the logic and challenge it.
Ownership. A public shareholder register and conflict-of-interest rules that can survive scrutiny.
Coverage. Early ratings for some of the 23 economies unrated by the big three, and the banks and companies inside them.
Stress behaviour. A record of publishing uncomfortable conclusions when a government, a lender or a shareholder would prefer silence.
Adoption should follow from those four. Central banks, pension regulators and development lenders may recognise AfCRA ratings if the agency earns that recognition.
The launch was a decision. The delivery, from Port Louis to the last mile, is the story ADC will keep tracking.